Source: Fortune
Summary
Redfin reported that 21.1% of U.S. home sellers with active listings reduced their asking prices in the four weeks ending Sept. 20, the highest share for this time of year since 2022. Denver had the highest rate at 30.9%, while San Francisco had the lowest at 9.6%. Redfin called the market a strong buyer’s market, but some economists question the label, noting tight inventory and high prices in certain regions. Mortgage rates have risen to 7.28%, complicating buying for those needing financing.
Our Reading
The numbers tell one story.
Sellers are cutting prices more than ever.
Buyers are stretched by high rates and limited budgets.
Some markets still feel tight despite the shift.
The buyer’s market is only for those who can afford it.
Author: Evan Null
Record Price Cuts, But Not All Markets Are Equal
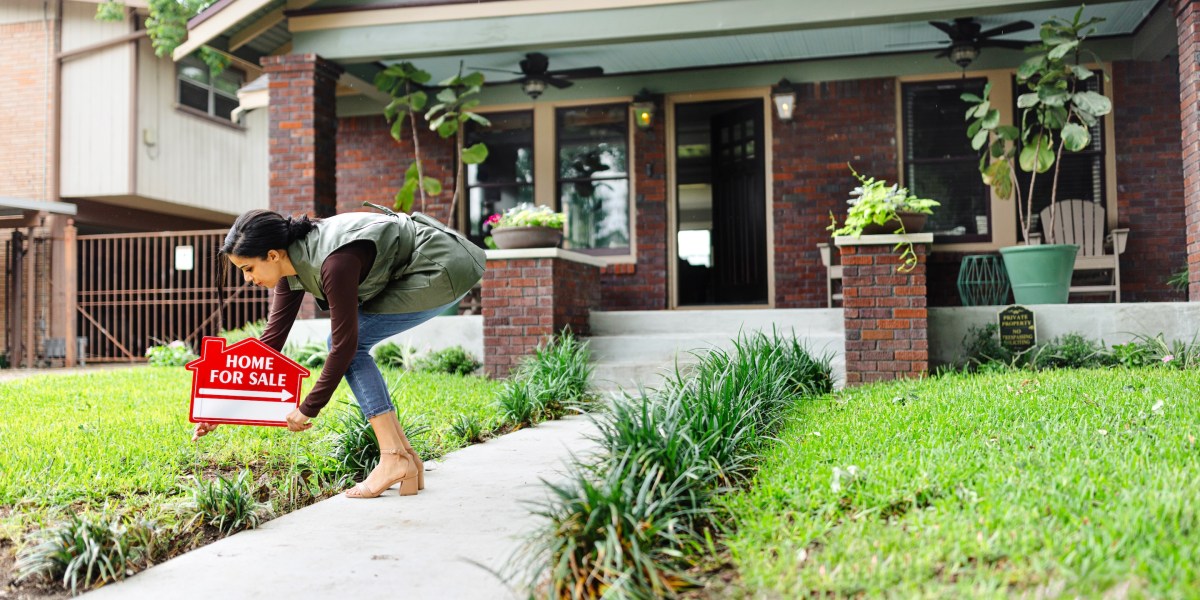
The share of U.S. home sellers cutting their asking prices reached a record high for this time of year, according to Redfin. In the four weeks ending Sept. 20, 21.1% of active listings saw price reductions, the highest level since Redfin began tracking the data in 2022. The trend is most pronounced in cities like Denver and Indianapolis, where over 29% of sellers adjusted their prices.
San Francisco, in contrast, had the lowest share of price cuts at 9.6%. The city, home to tech companies like OpenAI and Anthropic, has seen high-income workers investing in real estate, which has kept prices near record highs. Redfin’s analysis shows that only five of the 50 most populous metro areas are still considered seller’s markets.
While the national trend suggests a buyer’s market, local conditions vary. Lisa Sturtevant, chief economist at Bright MLS, said the label doesn’t fit all regions. She noted that inventory remains tight and prices are still high in the mid-Atlantic area. This highlights the gap between national data and local realities.
Mortgage rates have risen to 7.28%, the highest since November 2023, making it harder for buyers to qualify for loans. Sellers are adjusting by lowering prices, but many buyers are still struggling with affordability. The situation raises questions about whether the buyer’s market is accessible to all.
Experts suggest that all-cash buyers may have an advantage in the current environment. Research shows they often pay 10% less than mortgage buyers, as sellers prefer the certainty of cash transactions. However, the decision to pay cash depends on local market conditions and individual financial situations.
Buyer’s Market or Selective Advantage?
The data from Redfin paints a picture of a market shifting in favor of buyers, but the reality is more complex. While more sellers are lowering prices, the overall affordability challenge remains. High mortgage rates and limited buyer budgets mean that the benefits of a buyer’s market are not evenly distributed.
Some economists argue that the term “buyer’s market” is misleading in certain regions. In areas with tight inventory and high prices, the advantage is not as clear. Sellers may still hold strong positions, especially in markets where demand remains robust despite the price cuts.
The rise in price reductions has led to speculation about the role of all-cash buyers. With higher mortgage rates making financing more difficult, cash buyers are seen as a safer option for sellers. This trend could further tilt the market in favor of those with the financial means to buy without a mortgage.
Despite the shift, the market is still not universally favorable to buyers. Many are hitting the limits of their budgets, and the uncertainty around mortgage rates adds to the complexity. The question remains: is this a true buyer’s market, or just a selective advantage for some?
For now, the housing market is in transition. Sellers are adjusting to a more competitive environment, and buyers are navigating a landscape shaped by high rates and limited affordability. The final shape of the market will depend on how these factors evolve in the coming months.
High Rates and Price Cuts: A Tug of War
The combination of rising mortgage rates and increased price cuts has created a dynamic where sellers are under pressure to lower their asking prices, but buyers are still struggling with affordability. The average 30-year fixed mortgage rate reached 7.28% as of Oct. 1, a level not seen since late 2023. This has made it harder for many buyers to qualify for loans, even as sellers adjust their pricing strategies.
The situation has led to a mismatch between buyer demand and seller expectations. While more sellers are willing to cut prices, the overall market remains challenging for those who need financing. This has raised questions about whether the current environment is truly a buyer’s market or just a temporary shift in pricing dynamics.
For sellers, the pressure to lower prices is growing, especially in markets where inventory is increasing. However, in some areas, such as San Francisco, the demand from high-income workers has kept prices stable. This contrast highlights the uneven nature of the market shift.
As the housing market continues to evolve, the balance between buyer and seller power will likely remain in flux. The next few months will be critical in determining whether the current trends are a temporary adjustment or the start of a more permanent shift.
For now, the market is in a state of transition, with both buyers and sellers navigating a complex landscape shaped by high rates, changing inventory levels, and shifting buyer preferences.
Price Cuts and the Role of Cash Buyers
The increase in price cuts has led to renewed interest in all-cash buyers, who are seen as a more attractive option for sellers. According to research, cash buyers often pay 10% less than those using mortgages, as sellers prefer the certainty of a cash transaction. This dynamic could further benefit those with the financial resources to buy without a mortgage.
However, the decision to pay cash is not without its own challenges. Buyers must weigh the benefits of avoiding mortgage rates and loan approvals against the opportunity cost of tying up large amounts of capital. In a market where prices are still high in some areas, the financial burden of a cash purchase can be significant.
Despite the advantages, not all buyers have the option to pay cash. For many, the current market is still difficult to navigate, with high rates and limited affordability. This means that the benefits of the current environment are not evenly distributed, and the buyer’s market may only be accessible to a select group of buyers.
As the housing market continues to adjust, the role of all-cash buyers will likely become more prominent. However, the broader market will still be shaped by the interplay between rising rates, inventory levels, and buyer demand.
The current situation highlights the complexity of the housing market, where shifts in pricing and financing options are creating new opportunities and challenges for both buyers and sellers.
Market Shifts and the Future of Housing
The current housing market is undergoing a significant transformation, with more sellers adjusting their prices and buyers facing a mix of opportunities and challenges. While the shift in power from sellers to buyers is clear, the extent of that shift varies by region and market conditions. This has led to a more nuanced understanding of what it means to be in a buyer’s market.
The rise in price cuts is a clear indicator of increased competition among sellers, but it is not a guarantee of a more favorable market for all buyers. High mortgage rates and limited affordability continue to be major barriers, especially for those who rely on financing. This has created a situation where the benefits of a buyer’s market are not universally available.
As the market continues to evolve, the role of all-cash buyers is becoming more important. Their ability to navigate the current environment without the constraints of mortgage financing gives them a distinct advantage. However, this advantage is not accessible to all, and the broader market will still be shaped by the interplay between demand, supply, and financing options.
The future of the housing market will depend on how these factors continue to develop. For now, the market is in a state of flux, with both buyers and sellers adapting to a changing landscape. The next few months will be critical in determining whether the current trends are a temporary adjustment or the start of a more permanent shift.
For many, the housing market remains a complex and challenging environment. The combination of high rates, limited affordability, and shifting pricing strategies means that the benefits of the current situation are not evenly distributed. The final shape of the market will depend on how these factors continue to evolve in the coming months.