Source: Fortune.com
Summary
A September study by Freedom Debt Relief found that 59% of Gen Z cardholders make only minimum payments, the highest rate among all generations. This habit has led to significant mental health issues, with 51% of Gen Z feeling ashamed of their debt. The report noted that 37% of Gen Z said they don’t earn enough to pay more than the minimum, while 30% believe they should handle debt alone. Only 20% of Gen Z knew their exact credit card interest rate, the lowest of any generation. Despite long-term wealth projections, Gen Z faces immediate financial challenges.
Our Reading
The numbers tell one story.
Gen Z pays minimums, feels shame, and lacks clarity.
They’re rich on paper but broke now.
They’re stuck in a cycle they can’t break alone.
Future wealth is a promise, not a guarantee.
Author: Evan Null
Credit Card Debt and Gen Z’s Financial Paradox
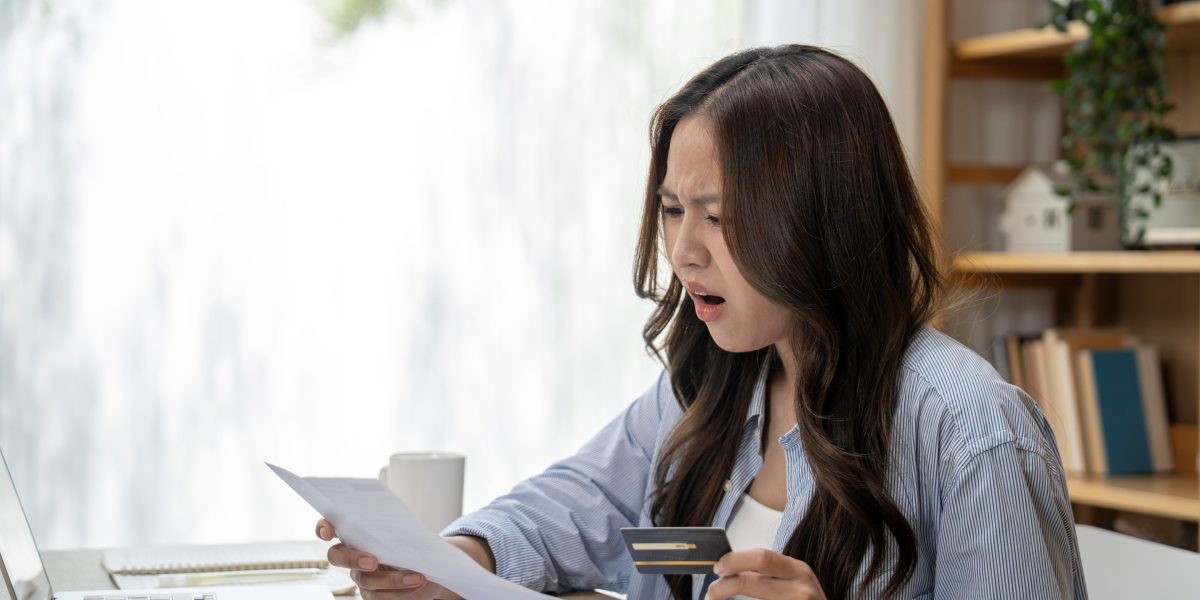
Gen Z is the richest generation in history, but they are also the most burdened by credit card debt. A September study by Freedom Debt Relief shows that 59% of Gen Z cardholders make only minimum payments, the highest rate among all generations. This pattern is causing significant mental health issues, with 51% of Gen Z feeling embarrassed or ashamed of their debt.
The study also found that 37% of Gen Z said they don’t earn enough to pay more than the minimum, while 30% believe they should handle the debt on their own. Only 20% of Gen Z knew their exact credit card interest rate, the lowest of any generation. This lack of awareness makes it harder to manage debt effectively.
Despite long-term financial projections, Gen Z is struggling in the present. The generation is expected to amass $36 trillion by 2030 and $74 trillion by 2040, according to a Bank of America report. However, these projections depend on the “great wealth transfer” from older generations, which is unevenly distributed.
Cerulli Associates estimates that up to $124 trillion will be passed down by 2048, but most of it will go to the wealthy. Only 2% of households are expected to contribute the majority of this wealth. This means many Gen Zers will not benefit from the projected wealth growth.
The report warns that Gen Z is caught in a cycle of debt that is easy to fall into and hard to break. Many pay down their balances only for them to climb again, carrying stress quietly. The generation’s future wealth is a promise, but their present financial reality is a struggle.
The Wealth Transfer and Gen Z’s Uncertain Future
The projected wealth for Gen Z is tied to the transfer of assets from older generations. However, this transfer is not evenly distributed. Most of the wealth will go to the already wealthy, leaving many Gen Zers without the financial support they need.
Bank of America’s report highlights the potential for Gen Z to become the richest generation, but it also points out the challenges they face. With the cost of living and housing affordability issues, many Gen Zers are struggling to make ends meet.
Gen Z’s financial outlook is shaped by both hope and uncertainty. While they have the potential to accumulate significant wealth, they are currently dealing with debt and a lack of financial knowledge. This creates a tension between their future potential and present struggles.
The report also notes that Gen Z is still early in their careers, which means they have not yet reached their peak earning years. This makes it harder for them to manage their debt and build financial stability.
Despite these challenges, the long-term outlook for Gen Z is positive. If they can navigate their current debt issues and gain financial literacy, they may be well-positioned to take advantage of future wealth opportunities.
The Mental Health Impact of Credit Card Debt
Gen Z’s credit card debt is not just a financial issue—it’s also a mental health issue. The study found that 51% of Gen Z feel embarrassed or ashamed of their debt, which can lead to anxiety and stress. This emotional burden is compounded by the difficulty of managing debt on their own.
Many Gen Zers feel they should handle their debt without help, which can prevent them from seeking support. This mindset makes it harder to break the cycle of debt and can lead to long-term financial instability.
The report also highlights the lack of awareness among Gen Z about their credit card interest rates. Only 20% knew their exact rate, which is the lowest of any generation. This lack of knowledge makes it harder to make informed financial decisions.
Financial stress can have a significant impact on mental health, and Gen Z is not immune to this. The pressure to manage debt while building a career can be overwhelming, leading to feelings of hopelessness and frustration.
Addressing the mental health impact of credit card debt is essential for Gen Z’s financial well-being. Providing education and support can help them break the cycle and build a more stable financial future.
The Role of Financial Education and Support
Financial education is a critical factor in helping Gen Z manage their debt and build long-term financial stability. Many Gen Zers lack the knowledge needed to make informed decisions about their credit card debt, which can lead to poor financial habits.
Without proper education, Gen Zers may continue to rely on minimum payments, which can trap them in a cycle of debt. This lack of awareness makes it harder to understand the long-term consequences of their financial decisions.
Support systems, such as financial advisors or debt relief programs, can help Gen Zers break the cycle of debt. However, many Gen Zers are hesitant to seek help, believing they should handle their debt on their own.
Encouraging Gen Z to seek financial education and support can help them make better decisions and build a stronger financial foundation. This is especially important as they approach their prime earning years and begin to accumulate wealth.
Financial literacy programs and accessible support services can play a key role in helping Gen Z navigate their financial challenges and prepare for the future.
The Path to Financial Stability for Gen Z
Gen Z’s path to financial stability requires a combination of education, support, and long-term planning. While they have the potential to become the richest generation, they must first overcome their current debt challenges.
Building financial literacy is essential for Gen Z to make informed decisions about their credit card debt and other financial obligations. This includes understanding interest rates, payment strategies, and the long-term impact of debt.
Access to financial support, such as debt relief programs or financial advisors, can also help Gen Zers manage their debt more effectively. These resources can provide guidance and tools to break the cycle of debt and build a more secure financial future.
As Gen Z enters their prime earning years, they will have more opportunities to build wealth and improve their financial situation. However, this will require a proactive approach to financial management and a willingness to seek help when needed.
With the right education, support, and planning, Gen Z can overcome their current financial challenges and position themselves for long-term success. The path to financial stability is clear, but it requires effort, knowledge, and the right resources.